Senior Quantitative Developer at Barclays · New York, NY

Shreejit VermaQuantitative Developer & Researcher

Quantitative Developer, Quantitative Researcher, and Quantitative Trading Engineer based in New York. I build low-latency C++ trading and risk systems: FRTB market risk engines at Barclays, automated market making at BNP Paribas, and an FPGA and kernel-bypass market-making system for my MS thesis, plus statistical arbitrage and ML-driven alpha research.

View Experience Key Projects shreejitverma@gmail.com

Shreejit Verma
  • $500M

    daily market-making volume

    C++ automated market-making stack, BNP Paribas CIB

  • $8.5B

    AUM merger-arbitrage book

    Systematic strategies, Versor Investments

  • 50%

    lower trade processing latency

    C++ trade pipelines, Bank of America FICC

  • +20%

    higher Sharpe ratio

    Regime-based C++ execution framework, backtested

Professional Experience

Barclays

Oct 2026 – Present
Senior Quantitative Developer (Contract), FRTB Market Risk | New York, USA (Hybrid)
  • Architecting low-latency C++ and Python distributed pricing and risk calculation pipelines, optimizing Expected Shortfall (ES), Default Risk Charge (DRC), and Non-Modellable Risk Factor (NMRF) simulations across multi-asset trading desks.
  • Engineering high-throughput aggregation engines for the Sensitivities-Based Method (SBM), Gross Jump-to-Default (JTD), and Residual Risk Add-on (RRAO).
  • Designing automated backtesting and P&L Attribution (PLA) test suites (Risk-Theoretical vs. Hypothetical P&L), establishing stable model eligibility pipelines and minimizing capital charge penalties across major trading desks.
  • Scaling real-time scenario generation and risk factor time-series pipelines across high-performance grid environments, integrating kdb+/q and distributed message queues to ingest multi-terabyte tick and pricing feeds for risk factor observability.
  • Partnering with Quantitative Research, Front Office Trading, Risk Methodology, and Model Risk Governance to implement, validate, and document Basel IV compliance frameworks for regulatory audits (Fed, PRA, FINMA).

BNP Paribas CIB

Feb 2026 – May 2026
C++ Quantitative Developer (Co-op), Automated Market Making | New York, USA
  • Built low-latency components of the automated market-making stack for the Prime Credit Market (average $500M of daily market-making volume), spanning real-time market-data ingestion, tick analytics, and pricing/execution paths.
  • Profiled and optimized the software hot path feeding FPGA-accelerated market-data handlers and quoting engines.
  • Integrated secure on-premise LLM tooling with Git/Jira/Confluence to automate code, testing, and documentation workflows.

LogiNext Solutions Inc.

Mar 2023 – Jul 2024
Senior Software Engineer, Analytics | Mumbai, India
  • Architected Map Construction, Map Routing, and Rich Vehicle Routing algorithms (3 nested NP-Hard problems) using CP-SAT constraint programming and convex optimization over PostGIS, MongoDB, and S3.
  • Led a 12-engineer team delivering a high-throughput geospatial mapping application platform.
  • Built an LLM-powered debugging and query-resolution tool used company-wide, cutting mean bug-resolution time by 80%.
Quantitative Developer, Merger Arbitrage and Stock Selection Portfolio | Mumbai, India
  • Developed and backtested systematic merger-arbitrage strategies for an $8.5 Billion AUM fund, improving alpha capture by 15%.
  • Built and deployed ML pipelines for Order and Execution Management Systems, increasing trade execution efficiency by 29%.
  • Designed an ESG-driven merger-arbitrage signal from pre- and post-merger statistics, later run as a standalone portfolio and embedded across existing portfolios.

Bank of America

Jan 2020 – Jul 2021
Senior Software Engineer, Fixed Income Commodities and Currencies (FICC) | Chennai, India
  • Engineered Python-based trading services enhancing storage, processing, matching, and execution of trades on QUARTZ.
  • Integrated C++ pipelines to store trades in the object-oriented database SANDRA, reducing trade processing latency by 50%.
  • Led the migration of 1 million+ lines of code to Python 3.8, enhancing scalability and execution efficiency by 40%.

Bank of America

Jun 2018 – Dec 2019
Senior Tech Associate, Data Analysis and Insight Technology | Chennai, India
  • Architected and developed an ML/AI platform to deploy predictive models, increasing decision-making accuracy by 67%.
  • Designed machine learning models for data validation rules prediction, reducing workload by close to 36 Full-Time Equivalents (FTEs).

Research

Thesis work and research systems, each with source code or a live tool.

Featured case study

Trishul: AI-Integrated FPGA for Market Making

MS Thesis, Stevens Institute of Technology

Oct 2025 – May 2026

Sub-10us hardware-software co-designed market-making system: Verilog ITCH 5.0 parsing, L2 book, fixed-point RL inference, and single-cycle pre-trade risk on the FPGA critical path, with a zero-allocation C++20 control plane using lock-free SPSC queues and kernel-bypass style polling.

C++20VerilogFPGAKernel BypassLimit Order BookRL

MS Thesis, WorldQuant University · Mar 2024 – Jun 2024

Real-time portfolio optimization with convex and non-convex methods, adaptive rebalancing, and multi-factor modeling across interest rate, FX, credit, and market risks.

Portfolio OptimizationCVXPYFactor Models

Research tool · runs on this site

Reproducible value-investing screen: a deterministic multi-factor scoring engine with published formulas, weights, and limitations, golden-value tests, and CSV export.

Open the platform

Key Projects

Execution, alpha research, and engineering projects. Cards with a GitHub icon link to the source.

C++ library · Sept 2025 – Dec 2025

Regime-switching execution framework selecting among passive, TWAP, and aggressive execution using microstructure-robust volatility estimators, a Gaussian HMM, and Hawkes-process liquidity stress detection: +20.0% Sharpe Ratio, -6.1% transaction costs, -20.1% CVaR.

C++17Execution AlgorithmsHMMRisk

Quant Researcher, WallStreetQuants · Jun 2025 – Aug 2025

120-day volume-momentum crypto portfolio strategy: 155.76% annualized return and 1.94 Sharpe Ratio post transaction costs, outperforming the Bitcoin buy-and-hold benchmark.

PythonBacktestingAlpha Research

Independent project · May 2026 – Present

Self-hosted, local-first AI workspace orchestrating LLM providers behind a unified API, with MCP tool-calling agents, RAG and persistent semantic memory, and hardware-aware deployment of quantized open-weight models; nothing leaves the host by default.

LLM InfrastructureMCPRAGAgents

Independent project · May 2026 – Present

Cross-platform agentic developer platform on NixOS with declarative configuration, multi-agent orchestration, isolated Git worktrees, autonomous task execution, and CI-gated shipping.

NixOSMulti-Agent SystemsDevEx

ESG Merger Arbitrage Strategy

Versor Investments · Apr 2022 – Jun 2022

ESG-driven merger-arbitrage strategy capturing the opportunity created by ESG scores on target and acquirer pre- and post-merger statistics; converted into a standalone portfolio and embedded across all existing portfolios.

ESGMerger ArbitragePortfolio Strategy

Financial Modelling using Stochastic Calculus

Modeled asset prices and derivative strategies with Brownian motion, GBM, Ito's Lemma, martingales, Girsanov's theorem, SDEs, and the Fokker-Planck and Kolmogorov equations for volatility and interest rates.

Stochastic CalculusDerivatives PricingPython

Blockchain in Retail

Jan 2018 – Mar 2018

Decentralized e-commerce platform securing and streamlining retail transactions with smart contracts, currency conversion, custom hashing, and matching algorithms.

BlockchainSmart ContractsSolidity

QS Rank Predictor

Jun 2017 – Jul 2017

Ensemble of deep neural networks predicting QS World University Rankings, with suggestions on the areas each institution should improve.

Deep LearningNeural NetworksPredictive Modeling

Technical Arsenal

Low-Latency Systems

  • C++20/23
  • Lock-free data structures
  • Memory pools
  • SIMD
  • Cache-aware design
  • DPDK / kernel bypass
  • FPGA (Verilog, VHDL)
  • TCP/IP, UDP multicast
  • Linux kernel and performance tuning

Programming Languages

  • C++
  • Python
  • C
  • Java
  • R
  • MATLAB
  • kdb+/q
  • OCaml
  • JavaScript / TypeScript
  • Verilog
  • VHDL
  • Bash

Quantitative Finance

  • Market microstructure
  • Market making
  • Execution algorithms
  • Statistical arbitrage
  • Derivatives pricing
  • Greeks
  • Factor modeling
  • Portfolio optimization
  • Risk management

Market Risk

  • FRTB (IMA / SA)
  • Basel IV
  • Expected Shortfall
  • DRC / NMRF
  • Sensitivities-Based Method
  • P&L Attribution
  • Backtesting

Mathematics & Statistics

  • Stochastic calculus
  • Probability
  • PDEs
  • Linear algebra
  • Markov chains
  • Time series analysis
  • Bayesian statistics
  • Numerical methods
  • Differential equations

Machine Learning & AI

  • PyTorch
  • TensorFlow
  • scikit-learn
  • XGBoost
  • Random forests
  • RNN / LSTM
  • Reinforcement learning
  • Clustering
  • NLP
  • LLMs, RAG, MCP agents

Data & Distributed Compute

  • NumPy, SciPy, Polars, pandas
  • Spark / PySpark
  • Dask
  • Hadoop
  • Kafka
  • ZeroMQ
  • Airflow
  • PostgreSQL
  • MongoDB
  • Cassandra
  • Redis
  • InfluxDB
  • SQL / BQL
  • FastAPI, REST APIs
  • Slurm
  • IBM Symphony

Systems & DevOps

  • Docker
  • Kubernetes / OpenShift
  • AWS
  • GCP
  • Serverless
  • CMake
  • Git
  • Jenkins
  • Ansible
  • CI/CD
  • Linux

Engineering Philosophy

The principles behind the systems above, each tied to where it was applied.

Education

Georgia Institute of Technology (Online)

Aug 2024 – Expected Dec 2026
M.S. in Computer Science, Specialization in Computing Systems

Coursework: Computer Networks, Advanced Operating Systems, Distributed Computing, Database Management Systems.

Stevens Institute of Technology

Aug 2024 – May 2026
M.S. in Financial Engineering
GPA 3.974/4.0

Coursework: Market Microstructure, Portfolio Theory and Applications, Algorithmic Trading Strategies, Multivariate Statistics.

WorldQuant University

Dec 2021 – May 2024
M.S. in Financial Engineering
GPA 86%

Coursework: Deep Learning for Finance, Financial Econometrics, Fixed Income, Equity, Portfolio Management, Risk Management.

Carnegie Mellon University, Tepper School of Business

Aug 2021 – Oct 2021
M.S. in Computational Finance (program withdrawn due to father’s illness)

Coursework: Investments, Statistical Machine Learning, Simulation Methods, Financial Computing, Algorithmic Optimization.

Vellore Institute of Technology

Jul 2014 – Sept 2018
B.Tech in Computer Science and Engineering
GPA 8.78/10.0

Coursework: Data Structures and Algorithms, Programming Language Translators, Natural Language Processing.

GitHub Impact

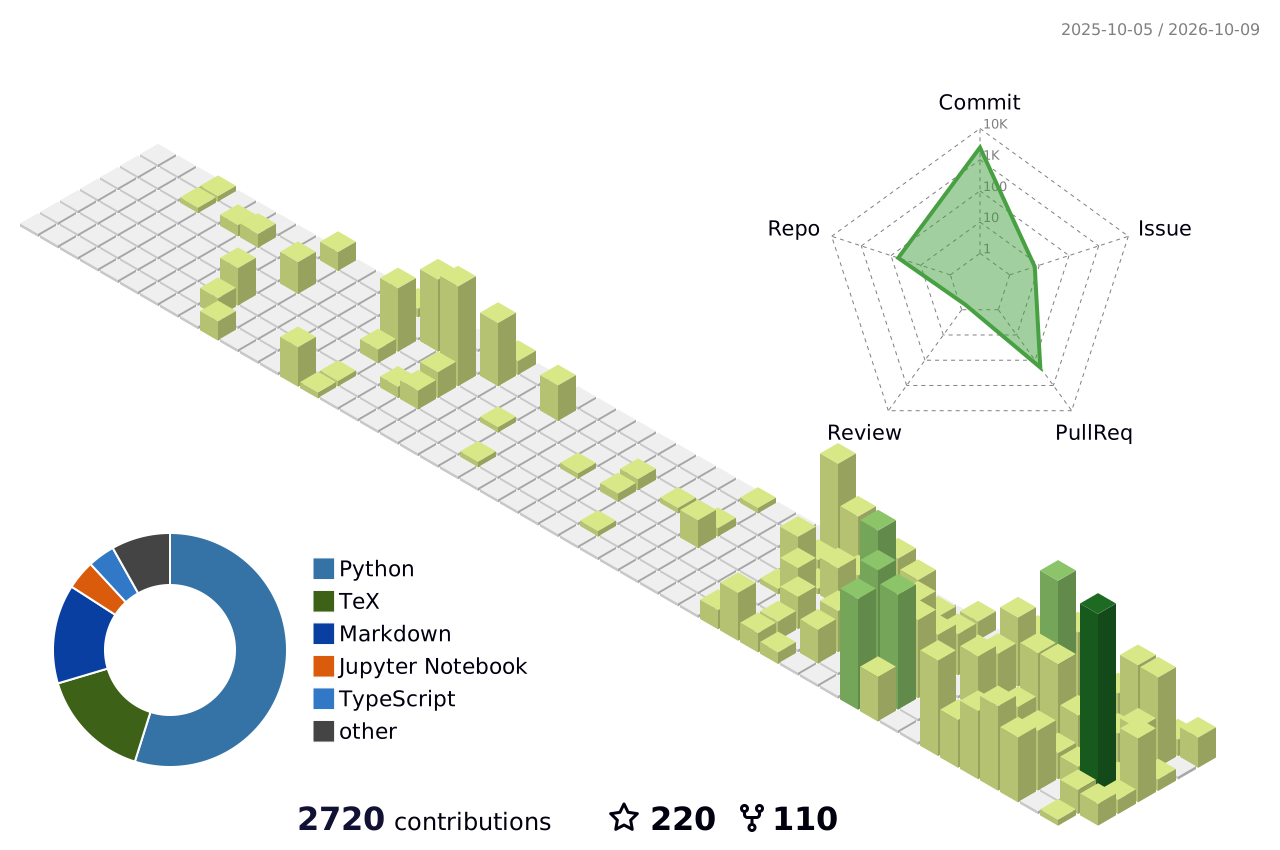
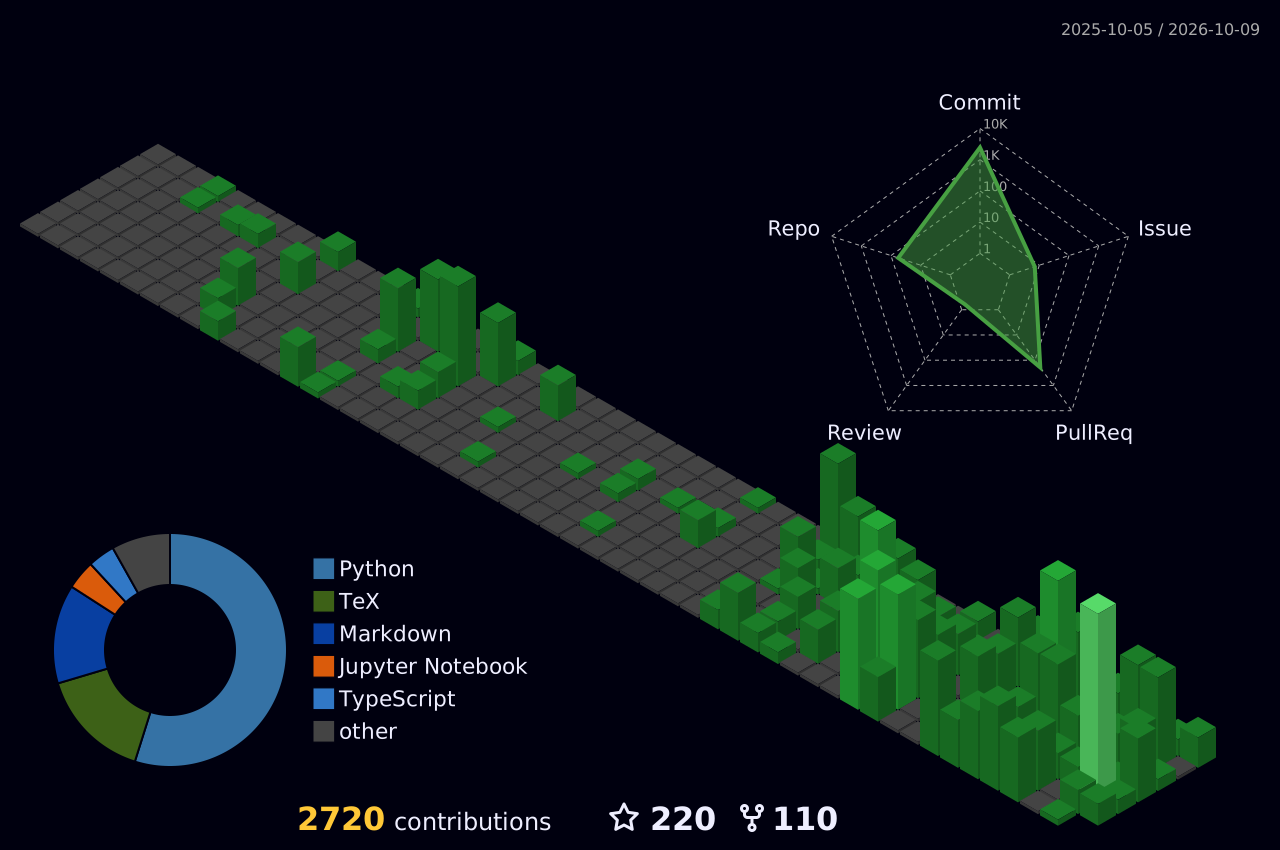
Activity across public and private repositories, refreshed daily from the GitHub API. View the GitHub profile.

  • 2,719

    contributions in the last year

    Across public and private repositories

  • 2,458

    commits in the last year

    194 pull requests and 7 issues opened

  • 188

    pull requests merged

    2 open, 5 closed without merge

  • 4d

    current contribution streak

    Longest in the last year: 9 days

  • 29

    repositories committed to

    66 public repositories, 189 stars, 89 forks

  • 2017

    on GitHub since

    86 followers

From the GitHub API, updated . Contribution counts include private repositories.

Languages

Share of commits in the last 12 months, by language

  • Python53.1%
  • JavaScript24.4%
  • C++11.7%
  • TypeScript6.1%
  • Shell1.9%
  • Java1.0%
  • C0.4%
  • Verilog0.3%
  • Other0.9%

Each repository's commits are split by its language mix; notebooks count as Python and markup is excluded.

Contribution streak: total contributions, current streak, and longest streak
Contribution calendar, commit streaks, and pull request status
3D contribution calendar for the last year
Animated snake eating the contribution graph
Profile visitor count

Writing

Awards & Leadership

Awards

  • 1st Place, Vanguard ETF Trading Challenge - Personal portfolio; 6th place for the team portfolio.
  • Global Recognition Gold Award, Bank of America - Led an enterprise-wide AI/ML campaign identifying 64 high-impact use cases; delivered AI/ML lectures to 2500+ employees across 4 events.
  • Global Recognition Silver Award, Bank of America (2x) - Total Return Swap post-trade processing contributions and an end-to-end in-house AI/ML framework.
  • President, Stevens Graduate Financial Association - Led the graduate finance student organization at Stevens.
  • Beta Gamma Sigma - International business honor society.
  • State Rank Holder - International Science Olympiad and International Mathematics Olympiad.

Interests & Languages

Interests

Chess, Poker, F1, Martial Arts, Cricket, Boxing, Badminton, Reading, Cooking, Dancing, Psychology, History, Philosophy

Languages

Fluent
English, Hindi
Intermediate
French, Sanskrit, Spanish, Russian
Beginner
Chinese, Italian, Tamil, Punjabi

Certifications

Essential Reading

A curated library of the books that shaped my trading philosophy and technical approach, from stochastic calculus to Eastern philosophy.

2,890 books across 10 shelves

  • Finance & Trading 774
  • Self-Help & Psychology 500
  • Computer Science & Data 310
  • Science & Math 281
  • History & Geopolitics 275
  • Business & Leadership 260
  • Philosophy & Spirituality 198
  • Fiction & Literature 146
  • Education & Reference 85
  • General 61
View Full Reading List
  • Encyclopedia of Chart Patterns cover

    Encyclopedia of Chart Patterns

    Thomas N. Bulkowski

  • Trading in the Zone cover

    Trading in the Zone

    Mark Douglas

  • The Intelligent Investor cover

    The Intelligent Investor

    Benjamin Graham

  • Technical Analysis from A to Z cover

    Technical Analysis from A to Z

    Steven B. Achelis

  • Super Trader cover

    Super Trader

    Van K. Tharp

  • High Probability Trading cover

    High Probability Trading

    Marcel Link

  • Options, Futures, and Other Derivatives cover

    Options, Futures, and Other Derivatives

    John C. Hull

  • Stochastic Calculus for Finance II cover

    Stochastic Calculus for Finance II

    Steven E. Shreve

  • The Man Who Solved the Market cover

    The Man Who Solved the Market

    Gregory Zuckerman

  • Machine Learning for Asset Managers cover

    Machine Learning for Asset Managers

    Marcos López de Prado

  • A Practical Guide to Quantitative Finance Interviews cover

    A Practical Guide to Quantitative Finance Interviews

    Xinfeng Zhou

  • Fooled by Randomness cover

    Fooled by Randomness

    Nassim Nicholas Taleb